
How North Atlanta Homeowners Typically Finance a Kitchen Remodel
Most homeowners settle on what they want long before they settle on how to pay for it. You've got a rough number in your head, you've been saving images for a year, and the thing that's actually holding up the project is the question of where the money comes from.
Before we get into it, here's what this is and isn't. Grand Home Design designs and builds kitchens across the North Atlanta Metro. We aren't a lender, a mortgage broker, or a financial advisor, and we don't have a stake in which option you pick. What follows is a plain description of the ways homeowners around here pay for this kind of work, plus something most financing articles skip entirely, which is what each choice does to the project once construction starts. For rates, terms, approval odds, and anything that touches your taxes, you'll want to talk to a lender and your accountant.
Here's what this guide covers:
The five ways homeowners around here pay for a kitchen remodel, and who each one actually fits
How your funding choice changes the way the project gets scheduled and paid
Why your approval amount isn't your budget
The sequencing problem that catches homeowners who talk to a bank before they talk to a designer
Answers to the financing questions homeowners ask most often
Grand Home Design serves Milton, Johns Creek, Alpharetta, Cumming, and the greater North Metro Atlanta region. Request a free design consultation or view our portfolio.
The Short (And most popular) Methods
In the mid to high five figure range, home equity and cash are what come up most often in conversations with homeowners, and they're frequently combined.
There's no single right answer here, and the differences between these options usually matter less than two things almost nobody talks about, which are whether your scope is finished before you borrow and whether you keep some money in reserve. Both of those come up further down.
If you're still working out what your project should cost before you work out how to pay for it, it's worth starting with the cost side.
Five ways North Atlanta homeowners pay for a kitchen remodel
Read these for the tradeoff rather than the pitch, because each one fits a different situation and none of them is universally better than the others.
Home equity line of credit (HELOC)
A HELOC lets you borrow against your home's equity repeatedly, drawing what you need when you need it, usually at a variable rate. The Consumer Financial Protection Bureau has a clear breakdown of how a HELOC differs from a fixed home equity loan, and it's worth ten minutes of your time before you talk to any bank.
The structure lines up well with how remodel money actually leaves your account, which is in stages rather than all at once. You're not paying interest on cabinetry money in month one when the cabinets don't get installed until month three.
There are two tradeoffs worth knowing about. A variable rate means your cost of borrowing can move during a project that spans several months, and a line that stays open after the job ends is easy to keep using, which is more of a discipline question than a lending question.
Home equity loan
This one gives you a lump sum with a set repayment term, usually at a fixed rate, though adjustable-rate versions do exist. If your rate is fixed, the payment won't change for the life of the loan.
A home equity loan rewards a finished scope and punishes a vague one. If you borrow before the design is settled, you'll either come up short, which means a second loan or a scramble, or you'll borrow more than the project needs and pay interest on money that just sat in a checking account. If you're going this route, you want drawings, selections, and a real proposal in hand first.
Cash-out refinance
With a cash-out refinance, you replace your existing mortgage with a larger one and take the difference at closing. Whether that makes sense depends almost entirely on how your current rate compares to what's available when you're reading this, which is why any article that gives you a number on this is already out of date. Run it with a lender rather than with a blog post.
The practical note for a remodel is that closing takes time and the money arrives all at once, so you'll want to plan the project timeline around that instead of assuming funds show up on demand.
Personal loans and contractor financing
Unsecured personal loans and third-party financing offered through a remodeler don't require home equity. Terms and rates vary quite a bit by lender and by borrower, and unsecured options commonly cost more than borrowing against the house. Some unsecured lenders will write larger amounts than people expect, so this isn't a category that's limited to small projects.
Grand Home Design doesn't offer or arrange financing, and that isn't a criticism of the companies that do. Financing offered through a contractor is a convenience, and it's worth comparing against what your own bank will do before you accept it.
The Federal Trade Commission maintains a consumer page on home improvement that covers payment practices and home improvement loan scams, including the pattern where a contractor arranges a loan secured against your house.
Cash, or cash plus a line of credit as a backstop
This is where a lot of projects in this budget range end up. Savings cover most of the work, and equity sits available in case something comes up.
Paying entirely in cash with nothing left over is a weaker position than financing part of the project and keeping a cushion, because remodels have a way of finding things inside walls. A 1970s ranch with original wiring behind the kitchen drywall doesn't care how you funded the cabinets.
What your funding source changes about how the remodel runs
This is the part lenders can't tell you and most remodeling blogs never get to, which is that the way you fund a project shapes how the project behaves.
A lump-sum loan pushes you to lock your scope early. That's genuinely good if the design is finished, and it's a problem if you're still deciding whether the wall comes down, because the number you borrowed is now fixed and the scope isn't.
A line of credit is more forgiving of a scope that develops as the drawings progress. It's also easier to let a project drift, since there's no moment where the borrowed amount forces a decision.
Remodel contracts are commonly structured as a deposit followed by payments tied to progress through the project, though the specifics differ between companies and between jobs. What matters for financing is the timing, because money needs to be available when phases complete rather than whenever a loan happens to close. If your funding arrives in one piece at a closing table six weeks out, then your start date is six weeks out too.
Contingency deserves its own paragraph here. Whatever you borrow or set aside for the project, some amount should sit outside it. Older housing stock across the north side hides surprises, and the expensive ones tend to involve electrical, plumbing, or structure behind a wall that was never meant to come down. A homeowner with reserve money gets to make a decision, while a homeowner who borrowed exactly the contract amount has to make a compromise.
Change orders are a common reason financed projects run short, and it usually isn't because anyone's being dishonest. A mid-project upgrade feels small in the moment, and by then there's no room left for it.
The point worth carrying out of this article is that the amount you can borrow isn't your budget. Design determines scope, scope determines the number, and borrowing capacity only tells you what's possible. Starting from an approval amount makes it easy to treat that figure as a target, and projects have a way of growing into whatever room you give them.Pull-out shelves and drawer conversions
Standard base cabinets with fixed shelves waste a surprising amount of usable space, because you can only reach what's in the front third of the cabinet without kneeling on the floor. Pull-out shelves solve this directly. Drawer conversions go a step further by replacing the cabinet door and fixed shelf setup entirely with deep drawers, which tend to work better for pots, pans, and small appliances than any shelf configuration.
Pull-out shelf conversions tend to cost less than options that require rebuilding the cabinet box itself, though a contractor can give you an exact range based on your specific cabinets.
The timing problem nobody warns you about
Lenders want a scope and a number. A real number requires measurement, drawings, and selections, which is another way of saying it requires design, and design takes time before anything gets demolished.
That creates a sequencing problem homeowners rarely see coming. They talk to a bank, get approved for an amount, and then discover that the project they actually want costs something different from the figure they'd been working with.
Running both conversations at the same time works better. If you start the design process and the lending conversation in parallel, then by the time you have a scope and a proposal you'll also know what you qualify for and on what terms.
There's one structural note about how design fits into all of this. At Grand Home Design, design is part of the remodel rather than something you buy separately. Karla designs every project herself, including the lighting, and she produces a rendering of the finished space before demolition starts. From a financing standpoint, that means you're looking at what you're paying for before the money gets committed to construction, which is a better position to be in than approving a scope from a line-item list.
Three things homeowners get wrong about paying for a remodel
The first is treating the approval amount as the budget. We covered this above, and it causes more trouble than anything else on this list. Approval tells you a ceiling, and it tells you nothing about what your house needs or what the project should be.
The second is applying national resale figures to a specific house. Published cost versus value data is aggregated across the country and across very different housing stock. A kitchen in a 2004 Milton build, and a kitchen in a 1962 Smyrna ranch aren't the same project and don't behave the same way at resale, so those figures work better as background context than as a projection for your address.
The third is assuming that cheaper financing produces a cheaper project. Scope decisions and rate differences both affect what a remodel costs you, but scope is the one you control directly while the design is still on paper. Cutting a change you didn't actually need is money that never enters the project at all.
Frequently Asked Questions
What credit score do you need to finance a kitchen remodel?
There's no single threshold, and it varies by product and by lender. Home equity products generally look at your credit alongside how much equity you have and your overall debt load, while unsecured personal loans lean more heavily on credit by itself. A lender can usually tell you where you stand pretty quickly, though it's worth asking whether the check is a soft inquiry or a full application, since the two affect your credit differently.
Is a HELOC or a home equity loan better for a kitchen remodel?
A HELOC suits a project where spending happens in stages and some details are still being worked out, while a home equity loan suits a project that's fully designed and priced and where you want the payment fixed and the scope locked. The CFPB comparison linked above lays out the mechanics of both without trying to sell you either one.
Can you finance a kitchen remodel with no equity in your home?
Yes, through unsecured personal loans or third-party home improvement financing. You should expect terms that reflect the lack of collateral, which generally means a higher cost than a secured option would carry. It's worth comparing at least two offers before you sign anything.
How much should you budget for unexpected costs during a kitchen remodel?
Set aside a contingency beyond your contract amount and keep it separate rather than mentally folding it into the project budget. The right figure depends on the age and condition of your house, since older homes with original systems behind the walls carry more risk than newer construction does. A designer walking your kitchen can usually tell you which category you're in.
Do remodelers require payment up front?
A deposit at signing is common, followed by payments tied to progress as the project moves through its phases. The specific schedule differs between companies and between projects, so ask for it in writing before you sign, and make sure the final payment comes after the work is complete and you've walked it.
Is a kitchen remodel worth it in the Atlanta market?
That depends on why you're doing it. If you're remodeling to sell within a year, the math is a resale calculation, and you should be talking to a real estate agent about your specific neighborhood before you talk to anyone about design. If you're staying, the return shows up as years of a kitchen that works the way your family actually uses it, and that's a different kind of value that no spreadsheet captures well.
Before you talk to a lender, know what you're building
The financing conversation gets much easier once the project is real. A lender can respond to a scope, a drawing set, and a number, but they can't do much with an idea and a range.
That's the sequence worth protecting. Figure out what the room should be, get it drawn, get it priced, and then decide how to fund it. The homeowners who end up frustrated almost always did it the other way around.
If you're in Marietta, Kennesaw, Roswell, Woodstock, Cumming, or anywhere else across the North Atlanta Metro and you want a real scope to take to your lender, get in touch with Karla.
Ready to Take The Next Step?
If you're trying to figure out which category your kitchen falls into, you can see examples of past kitchen work in our portfolio or learn more about how we approach kitchen remodeling in Atlanta.
Schedule a Consultation or call to talk through your project today.
The Person Behind the Work
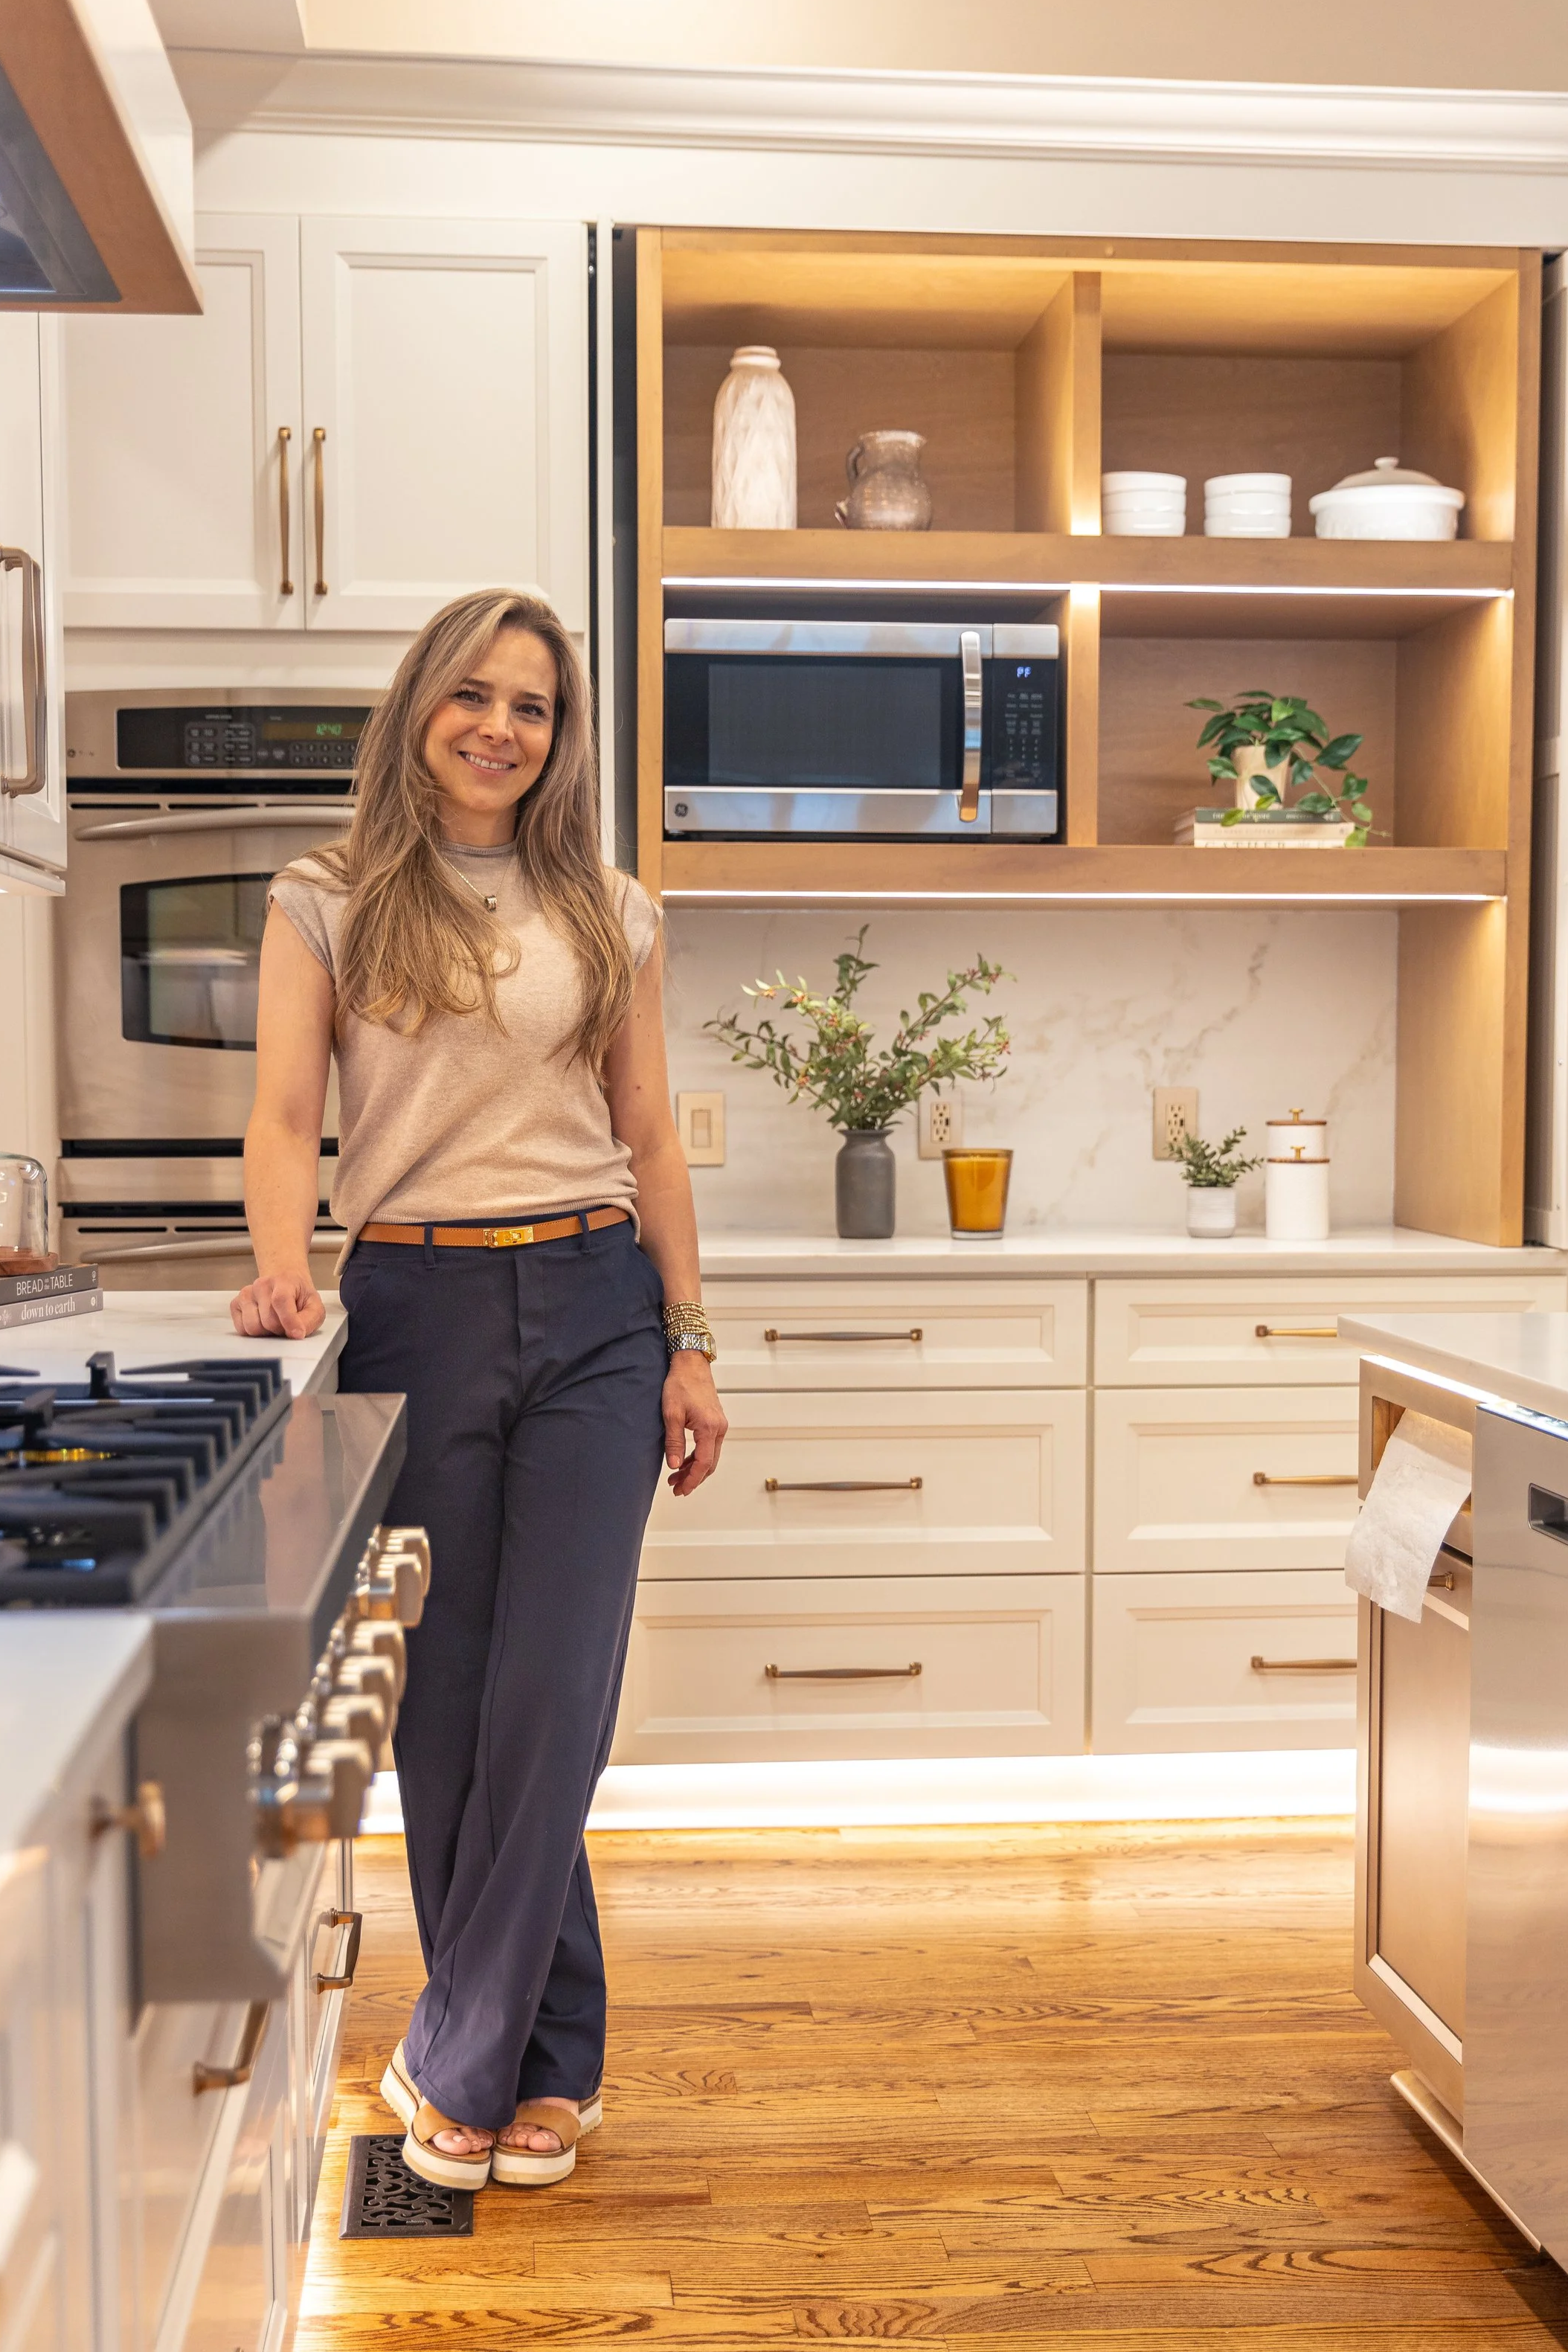
Karla Caudill brings more than two decades of design experience to each project, including work across Atlanta and North Metro communities. Her experience in North Fulton has given her a practical understanding of Milton homes, from large estate properties to family-oriented floor plans.
She is involved in the design conversation on every project, which gives clients direct access to the person shaping the plan.
Start Your Kitchen Consultation
Use the button below to fill out our short consultation form, and our team will reach out to discuss next steps.